DTI: How Car Loans and Credit Cards Change What You're Approved For
A $450 car payment can cost you $70,000 of house. Here's the number that matters most after your income.
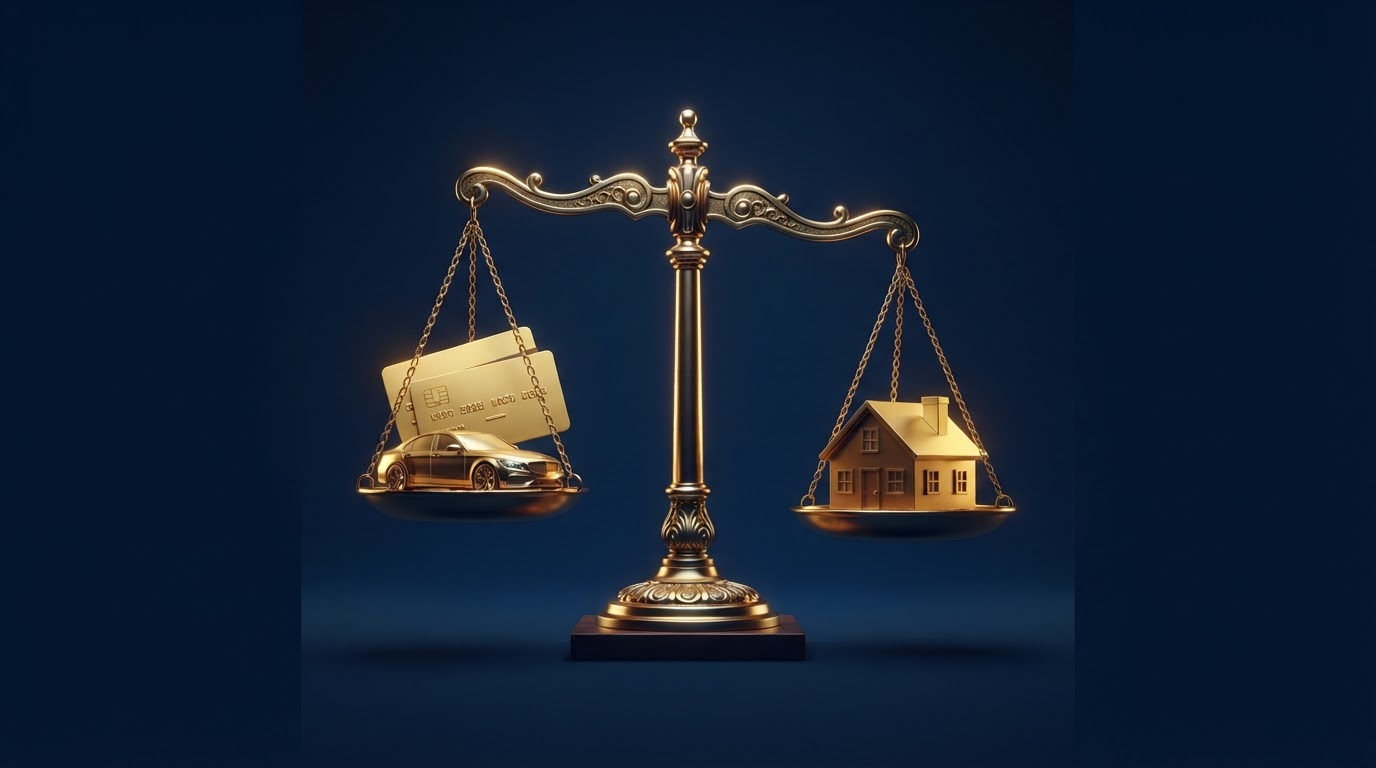
Clients come in convinced their credit score is the problem when the real problem is the car payment. Your score decides your rate; your DTI decides how much house you can buy. And most people have never heard the word.
What DTI is, in one line
DTI (debt-to-income) is all your monthly debt payments divided by your gross monthly income. A lender adds up your car, cards, personal loans, student loans and the new housing payment, and divides by what you earn before taxes.
Example: $7,000 gross, $450 in debts, $3,050 in housing → $3,500 / $7,000 = 50% DTI.
Most programs approve up to 45%–50%. Above that you need compensating factors: reserves, a long clean history, a bigger down payment.
What each debt costs you in house
| Extra monthly debt | House you lose (approx.) |
|---|---|
| $100 | ~$16,000 |
| $300 | ~$47,000 |
| $450 | ~$70,000 |
| $600 | ~$94,000 |
At 6.5% over 30 years, every $100 of monthly payment buys roughly $15,800 of loan. That's the exchange rate nobody shows you.
How lenders actually count each debt
- Credit cards: the minimum payment on the statement, not what you pay. Carrying $8,000 across three cards can be $240 a month whether you pay $240 or $600.
- Car loans and leases: the full contractual payment, including the lease.
- Student loans: the payment on the credit report, or 0.5%–1% of the balance when the report shows $0 — deferment does not remove it. That's covered in student loans in deferment.
- Personal loans, furniture financing, timeshare: all of it.
- Utilities, phone, insurance, groceries: not counted.
- 401(k) loans: usually not counted, but confirm with me before you take one.
Want to know your DTI right now?
Send me your income and your monthly payments and I'll calculate it in one message, plus how much house each debt is costing you.
Three mistakes that cost real money
- Closing a credit card to "clean up." It can lower your available credit and hurt your score. Pay it down, don't cancel it.
- Financing furniture or a car before closing. A new $400 payment mid-process can sink an approval that was already issued. This is the #1 item in what not to do between pre-approval and closing.
- Paying cards with a consolidation loan a week before applying. Sometimes it helps the DTI; sometimes the new loan and the old balances both show up. Timing matters, and it's worth a call first.
How to lower your DTI on purpose
- Kill the smallest balance first. A $70 card minimum disappearing can be worth thousands in buying power.
- Pay down revolving debt instead of saving a bigger down payment. It often moves the number further.
- Add a co-borrower with clean income.
- Document more income. Overtime, bonuses, self-employment: what counts depends on how it's proven: self-employed mortgages.
Then check the other side of the equation
DTI is only half the picture; the other half is what percentage of your income should go to housing at all: the 28/36 rule. And the full affordability math is in how much house can I afford.
Let's fix the number, not just measure it
I'll show you which debt is costing you the most house and what to do in the next 30 days. No credit pull, no obligation.
Paying off a $70 card minimum is not glamorous. But it can be the difference between the house you want and the house you settle for.
Run your numbers
Your next step
Want to know your DTI right now?
I'll calculate your DTI and show you how much house each debt is costing you. No credit pull, no obligation.