VA Loans in Houston for Veterans and Service Members
Your VA home loan benefit, put to work. VA loans offer 0% down for eligible veterans, active-duty service members, and surviving spouses — backed by the federal government, with no monthly mortgage insurance. We handle your entitlement and documentation from the first call.
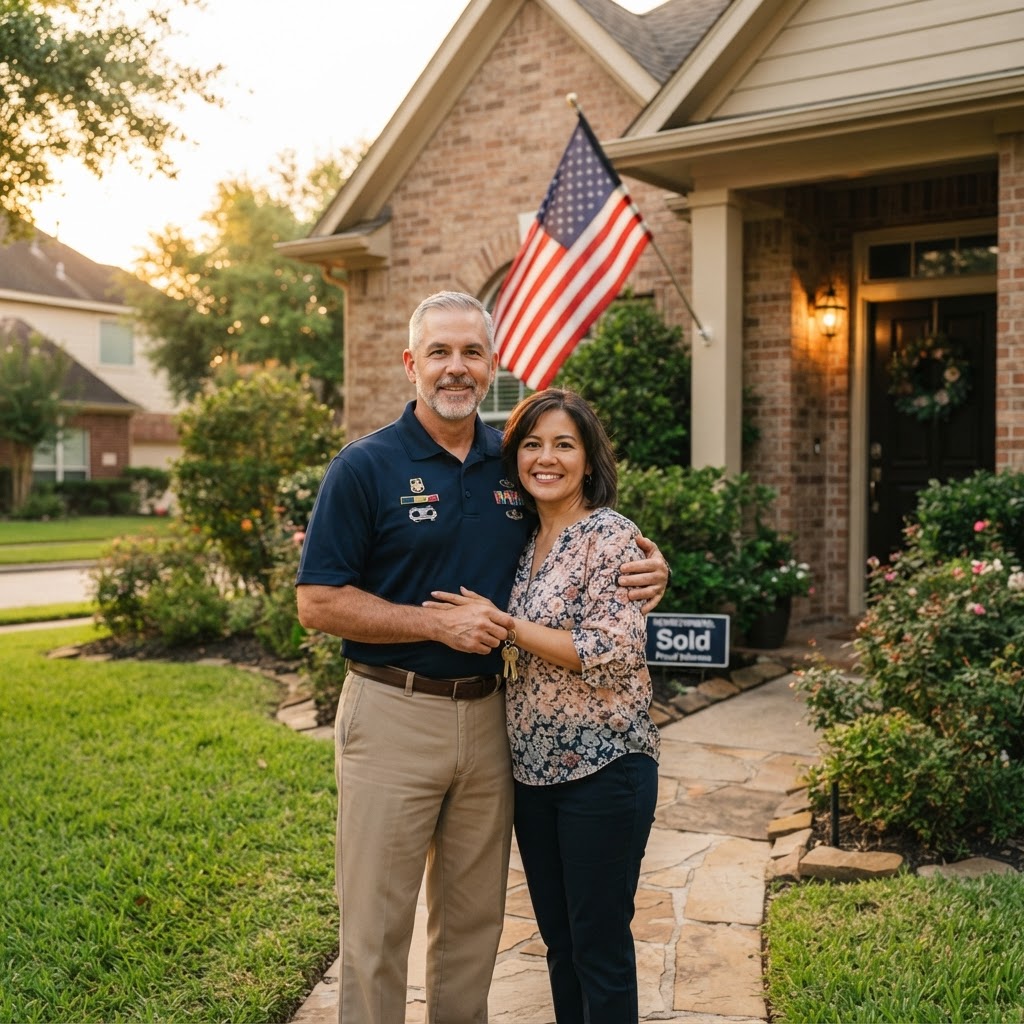
What is a VA loan?
A VA loan is a mortgage guaranteed by the U.S. Department of Veterans Affairs for eligible veterans, active-duty service members, and certain surviving spouses. It can allow 0% down with no monthly mortgage insurance — a benefit earned through service.
The VA guarantees a portion of the loan, which lets approved lenders offer terms few other programs include: no down payment requirement, no monthly mortgage insurance, and limits on certain fees a buyer can be charged.
Most VA loans include a one-time funding fee paid to the VA, which varies with down payment and prior use of the benefit. Many veterans receiving compensation for a service-connected disability are exempt from the fee entirely. Eligibility starts with a Certificate of Eligibility (COE), which a lender can usually pull electronically in minutes.
VA at a glance
VA loans: did you know?
A few facts that make VA the most powerful purchase loan for those who earned it.
True 0% down
With full entitlement, a VA loan finances 100% of the purchase price or appraised value, whichever is lower. No other common loan does that without monthly mortgage insurance.
No monthly mortgage insurance
VA loans have no PMI and no monthly MIP. The one-time funding fee replaces it — and disabled veterans are often exempt from even that.
The funding fee drops with down payment
Put down 5% and the funding fee drops; put down 10% and it drops again. Below 5% the fee stays flat. Putting even a little down can lower your cost.
Disabled veterans can be exempt
Veterans receiving VA compensation for a service-connected disability are generally exempt from the funding fee — which can save thousands at closing.
The benefit is reusable
You can use your VA loan benefit more than once. Entitlement can be restored after you sell and pay off a prior VA loan, so the benefit is there for your next home too.
Sellers can pay your closing costs
VA allows the seller to contribute up to 4% of the purchase price toward your closing costs and prepaid expenses — a real help on a 0%-down purchase.
VA Payment Calculator
Includes the one-time VA funding fee (financed into the loan) and shows $0 monthly mortgage insurance — the two numbers that make VA unique. Toggle the disability exemption to see the fee disappear.
VA Payment Calculator
Includes the one-time VA funding fee (financed into the loan) and shows $0 monthly mortgage insurance — the two numbers that make VA unique. Toggle the disability exemption to see the fee disappear.
Estimated Monthly Payment
$2,625
PITI · no monthly MI
- Principal & Interest
- Property Tax
- Insurance
Estimate only. VA funding fee rates vary by down payment, prior use of the benefit, and disability status; the rates shown are 2026 purchase rates for loans above $150k. Veterans receiving VA disability compensation are generally exempt. VA loans have no monthly mortgage insurance. Not a commitment to lend; your actual rate, funding fee, and terms depend on your full file and COE.
Who a VA loan often fits
- Eligible veterans and active-duty service members buying a primary home.
- Buyers who want to keep savings intact with 0% down and no monthly mortgage insurance.
- Surviving spouses who qualify for the VA benefit.
- Disabled veterans who may be exempt from the funding fee.
- Anyone who has earned the benefit and wants the lowest-cost purchase loan available.
VA loan FAQ
The VA itself sets no minimum credit score. In practice most VA lenders look for around 620, and some will consider scores down to about 580 when the rest of the file is strong. Your full picture — income, debts, and payment history — is always part of the review.
Educational content only. This page is not financial, legal, or tax advice, a commitment to lend, or an offer of credit. Program requirements and terms vary by lender and change over time; figures cited reflect the sources below as of the dates noted, and eligibility always depends on your full financial profile. Liuver Duran, NMLS #2579601. Sociable Mortgage LLC, NMLS #2498240. Equal Housing Opportunity.
Sources
Down payment assistance can cover your closing costs
A VA loan needs no down payment, but closing costs still apply. In Texas and Florida there are grants and second-lien programs that can cover those costs on a VA purchase — and sellers can contribute up to 4% on top. See what is available in your county.