Buy a Duplex with a VA Loan — and Let the Rent Help You Qualify
Yes, it's possible. If you're a veteran or active-duty service member, you can buy a 2-to-4 unit property with $0 down and use the projected rental income from the other units to help you qualify for the mortgage. Here's exactly how it works.

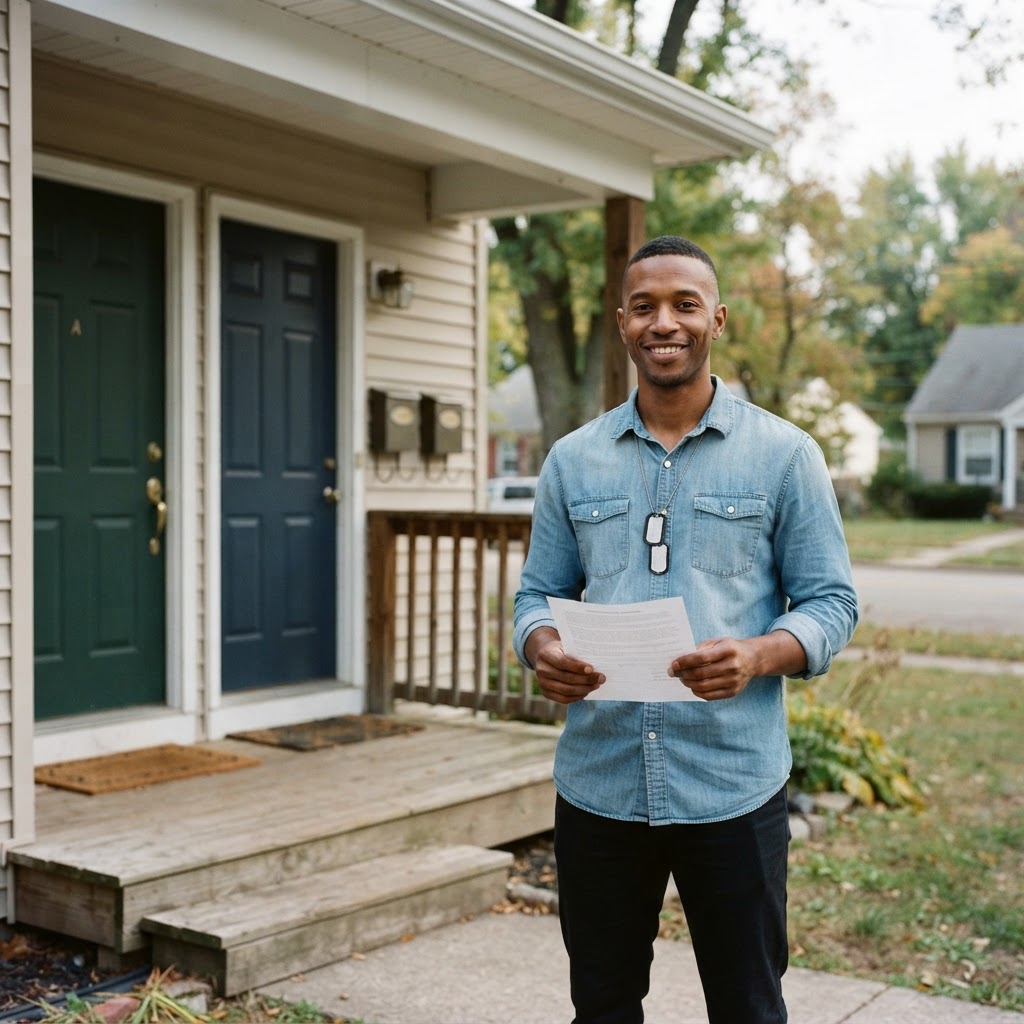
Imagine this: you serve in the military, you've earned your VA benefit, and you're looking at a duplex for $380,000. One side for you and your family. The other side already has a tenant paying $1,400 a month. That rent doesn't just help with the mortgage — it could actually help you qualify for the loan. That's not a trick. That's the VA loan working exactly as it should.
A lot of veterans I talk to don't know this is even possible. They think the VA loan is only for a single-family home where they'll live alone. But the rules are broader than that — and when you know how to use them, this benefit becomes one of the most powerful wealth-building tools available.
Let me walk you through how it actually works, what the lender looks at, and where the limits are. No fluff, just the real picture.
What Types of Multi-Family Properties Can You Buy with a VA Loan?
The VA allows you to purchase a property with up to 4 units — as long as you move into one of them as your primary residence. That means:
- A duplex (2 units)
- A triplex (3 units)
- A fourplex (4 units)
You cannot buy a 5-unit apartment building with a VA loan. But a fourplex where you live in unit one and rent out the other three? That's 100% within the rules.
The key requirement: you must occupy one unit as your primary residence within 60 days of closing. The VA isn't in the business of financing pure investment properties — but they're perfectly fine with you being an owner-occupant who also happens to be a landlord.
Can the Rental Income Actually Help You Qualify?
Yes — but with conditions. This is where a lot of people get confused, so I'll be direct.
Lenders can count projected rental income from the units you won't be living in to help offset your debt-to-income ratio (DTI). Here's how it typically works:
- The appraiser completes a rental income analysis (usually on Fannie Mae Form 1025 or a VA equivalent).
- The lender can count roughly 75% of the projected market rent from the other units as income. The 25% haircut accounts for vacancies and maintenance.
- That counted income reduces your effective housing cost in the DTI calculation.
Real example: Say you're buying that $380,000 duplex. Your PITI (principal, interest, taxes, insurance) payment comes out to about $2,400/month. The appraiser determines the rental unit should rent for $1,400/month. The lender can count 75% of that — or $1,050 — as income. Your net housing cost for DTI purposes drops to roughly $1,350 instead of $2,400. That can make a serious difference if your qualifying income is, say, $6,000/month.
See If Your Income + Rental Income Gets You There
Run your scenario with Liuver — no pressure, just real numbers.
What the Lender Needs to Make It Work
Not every lender handles this the same way. Here's what most will want to see:
- A VA appraisal that includes a market rent schedule
- Documentation that the units are legally separate (separate entrances, separate meters preferred)
- In some cases, evidence of prior landlord experience — though this isn't always required
- A signed lease if the unit is already occupied (this actually helps a lot)
If you're buying a duplex that already has a paying tenant with a lease in place, you're in a stronger position. That's documented income, not just a projection.
The One Honest Downside I Always Mention
VA loans on multi-family properties are not common, and not every lender knows how to process them correctly. If the loan officer you're talking to seems confused by the question, that's a signal.
Work with someone who has done this before. The VA benefit is yours — you earned it — and it should work for you, not against you because of a paperwork error.
Ready to Find Out If This Works for Your Situation?
Here's the short version: yes, you can use a VA loan on a duplex, triplex, or fourplex. Yes, rental income from the other units can help you qualify. And no, you don't need a down payment to do it.
If you want to run your specific numbers — your income, the property type, the expected rent — I'm happy to walk through it with you. No sales pitch. Just an honest look at whether the numbers work.