Can You Get a Mortgage on a Condo, Manufactured Home, or Barndominium?
Not every property gets approved the same way. Here's what you need to know before you fall in love with a home that might be harder to finance.
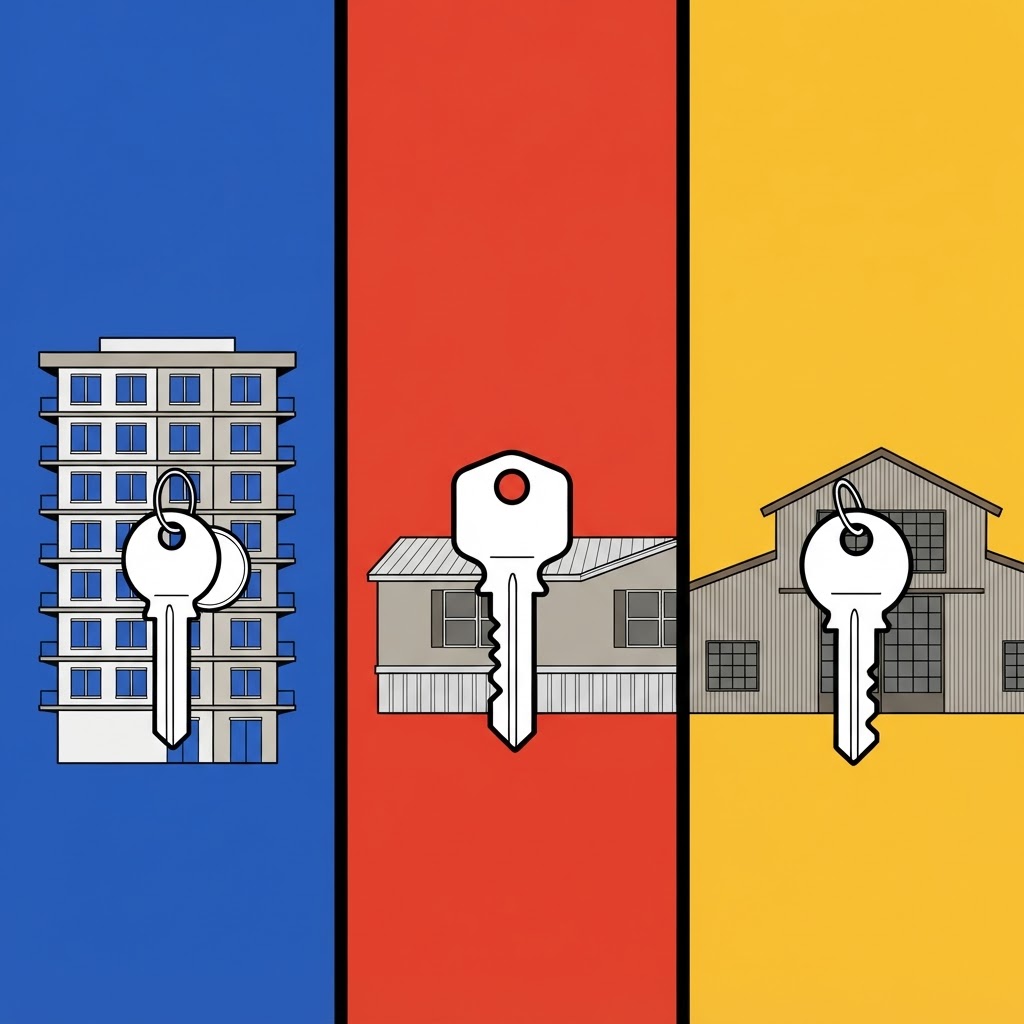
You found the perfect place — a cozy condo downtown, a brand-new manufactured home in a quiet community, or maybe a barndominium on a few acres outside the city. The price looks right, the space feels right. Then someone says: "I'm not sure you can get a mortgage on that." And suddenly the whole dream gets foggy.
I hear this all the time. And honestly? It's one of the most common things that slows buyers down — not the money, not the credit, just the confusion about what kinds of homes actually qualify for a mortgage. So let me clear this up for you, the same way I do for my clients.
The short answer is: yes, you can get a mortgage on a condo, a manufactured home, and even a barndominium — but each one has its own rules, and knowing them ahead of time saves you a lot of headaches.
Can You Get a Mortgage on a Condo?
Yes — and it's more common than people think. But there's a catch: the condo itself has to be approved, not just you.
Lenders look at the whole building or complex, not just your unit. They want to know:
- What percentage of units are owner-occupied vs. rented out
- Whether the HOA is financially healthy
- If there are any major pending lawsuits against the association
- How many units are owned by one single investor
For example, if a complex has 100 units and one investor owns 30 of them, that's a red flag for most conventional loans. But there are flexible options — FHA-approved condo lists exist, and some loan programs are more forgiving on these details.
A realistic scenario: a $280,000 condo in Miami with a 3.5% down payment under an FHA loan means roughly $9,800 out of pocket to start. If the condo is approved and your credit is 580 or above, it's a workable deal.
What About Manufactured Homes? They're Not the Same as Mobile Homes
A lot of people mix these up, and it matters. A manufactured home built after June 15, 1976 follows HUD construction standards and can absolutely qualify for a mortgage — including FHA, VA, and conventional loans.
What lenders care about most:
- The home must be on a permanent foundation
- It must be classified as real property, not personal property (meaning it's titled like land, not like a vehicle)
- The home itself must meet minimum size requirements (usually at least 400 sq ft)
If the home is still on a rented lot inside a park, financing gets more complicated — but it's not impossible. There are chattel loans for that situation, though the rates are typically higher.
Real example: a $150,000 manufactured home on owned land with a 5% down payment is $7,500. Monthly payment at a 7.25% rate over 30 years lands around $950/month — often less than rent in the same area.
Not sure if your home qualifies?
Tell me the property type and I'll let you know what loan options you have — no pressure, no sales pitch.
Barndominiums: Cool Homes, Tricky Financing
I want to be honest with you here — barndominiums are the most challenging of the three. Not impossible, but they require more legwork.
The challenge is appraisal. Lenders need comparable sales (comps) to determine the home's value, and in rural areas, there often aren't many barndominiums to compare to. That can make some lenders hesitant.
What actually works:
- USDA loans can work if the property is in an eligible rural area
- VA loans are an option for veterans if the appraiser can find comps
- Portfolio lenders (banks that hold their own loans) are often more flexible
- Conventional loans are harder but not out of the question with the right appraiser
If you're set on a barndominium, plan early. Financing one takes 45–60 days on average, sometimes more.
Thinking about a barndominium or rural property?
I work with lenders who understand non-traditional homes — let's talk before you make an offer.
Next Steps: Know Your Property Before You Fall in Love
Here's the honest truth — the home type matters just as much as your credit or income when it comes to qualifying for a mortgage. A little research before you make an offer can save you from a really frustrating situation.
If you're looking at a condo, ask if it's FHA or conventional-approved. If it's a manufactured home, confirm it's on a permanent foundation. And if it's a barndominium, come talk to me first.
I'm Liuver, loan officer with The Trusty Lender. I work with buyers of all backgrounds, all credit situations, and all property types. Send me a message — just tell me what you're looking at and where, and I'll give you a straight answer on what's possible.